Tax Exemption Operations for Overseas Enterprises' Technology Imports After the 'VAT Reform'
Before the pilot program of replacing business tax with value-added tax ('VAT Reform'), overseas enterprises transferring technology or providing technical services to domestic entities could enjoy business tax exemption treatment. After the VAT Reform, whether overseas enterprises could continue to enjoy the relevant tax exemption treatment became a subject of widespread debate. In response, based on research into policies and regulations as well as communication with tax authorities, we provide a brief introduction to the relevant tax exemption policies and specific operations for overseas enterprises' technology imports after the VAT Reform.
I. Overseas Enterprises' Technology Imports May Enjoy VAT Exemption Treatment After the VAT Reform
Following the VAT Reform, there has been significant disagreement regarding whether overseas enterprises' technology imports may enjoy VAT exemption treatment. The source of disagreement lies in the provisions of the State Administration of Taxation's 'Interim Management Measures for Tax Exemption and Export Tax Rebate for Zero-Rate VAT Applicable Services in VAT Reform Pilot Areas' (Guo Shui Fa [2012] No. 13), which stipulates that the scope of zero-rate VAT applicable services is limited to R&D services and design services provided by domestic enterprises to overseas entities. Therefore, some believe that only when domestic enterprises export technology to overseas entities can they enjoy VAT exemption treatment, while overseas enterprises importing technology to domestic entities cannot enjoy exemption treatment. We believe this conclusion is one-sided, for the following reasons:
1. Zero-rating does not equal exemption. Zero-rating means that taxable goods/services within the scope of collection are completely tax-free; while exemption means that taxable goods/services that should be taxed are not taxed at this stage. Therefore, even though zero-rate taxable services are limited to R&D and design services provided by domestic enterprises to overseas entities, this does not exclude overseas enterprises' technology imports from enjoying exemption treatment.
2. The 'VAT Reform Pilot Program' (Cai Shui [2011] No. 110) issued by the Ministry of Finance and the State Administration of Taxation clearly establishes the principle of transitional tax preferential policies, namely that the original business tax preferential policies granted by the state to pilot industries may continue.
3. The 'Notice on Conducting the VAT Reform Pilot for Transportation and Logistics and Selected Modern Service Industries in Shanghai' (Cai Shui [2011] No. 111) issued by the Ministry of Finance and the State Administration of Taxation also clearly states: 'Pilot taxpayers providing technology transfer, technology development, and related technical consultation and technical services are exempt from VAT.' Pilot taxpayers include not only domestic taxpayers but also overseas taxpayers.
Therefore, after the VAT Reform, overseas enterprises' technology imports may still enjoy VAT exemption treatment. Specifically, when overseas enterprises receive taxable income from technology transfer, technology development, and technical consultation services provided to domestic entities, they may still enjoy VAT exemption treatment after the domestic entities receiving the technical services, as withholding agents, file for tax exemption with the relevant Chinese government departments on their behalf.
II. How Overseas Enterprises' Technology Imports File for Tax Exemption After the VAT Reform
Taking Shanghai as an example, the current process for overseas enterprises' technology imports to file for tax exemption is as follows:
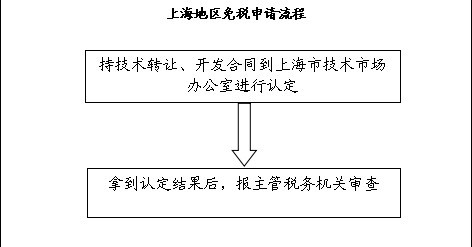
According to the current operational process, to file for overseas enterprises' technology imports tax exemption in Shanghai, the following documents mainly need to be submitted to the competent tax authority:
1. Application for tax exemption
2. 'Tax Exemption Application Filing Form'
3. Original and copy of the business contract for technology transfer, technology development, and related technical consultation and technical services
4. 'Technology Transfer Contract' and 'Technology Transfer Contract' reviewed and stamped with the special seal for technology transfer contract certification of Shanghai Technical Market Management Office or the special seal for technology development contract certification of Shanghai Technical Market Management Office, with the examiner's seal, as well as the original and copy of the technology contract registration certificate
5. Copy of business license and tax registration certificate.
After the tax authority reviews and confirms the above documents are correct, it will grant overseas enterprises' technology imports VAT exemption treatment. It is believed that the preferential tax policies for overseas enterprises' technology imports after the VAT Reform will continue to optimize the international technology import and export environment, promote the development of technology import and export, and further consolidate and enhance Shanghai's frontier position as a core city for technology import and export in China.